August 17, 2026 7 mins
From Strong Returns to Sustainable Advantage: What Insurers Should Do Next as Market Conditions Change

Insurers' return on equity reached 16.8% in 2025, its highest level since 2009. But premium has growth slowed and insurers face a new challenge: sustaining growth and delivering consistent performance through the cycle.
Key Takeaways
-
Profitability has reached a new peak. Return on equity reached 16.8% in 2025, the highest level since Aon began tracking the cohort in 2009, creating strategic options for sustainable profitable growth.
-
Growth is becoming harder to sustain. The gap between growth and profitability continues to widen, creating a different operating environment and new strategic questions for insurers.
-
As favourable market conditions fade, outperformance will depend on avoiding the pitfalls that erode value – such as overestimating growth, misallocating capital and failing to make effective use of AI – while making better decisions on growth and capital.
One Year Later: What’s Changed?
Aon's Strategy and Technology Group analyses the performance of 120 global property and casualty insurers to assess how profitable growth outcomes are evolving through the market cycle.
Last year, we argued that insurers needed to balance growth, profitability, capital and resilience in a market defined by inflation, catastrophe losses, capital constraints and significant rate correction. We also continue to reinforce the seven traits shared by insurers that consistently outperform through the cycle.
Twelve months later, many of those pressures remain. But the question has evolved. Our latest analysis suggests insurers are entering a new phase of the cycle where profitability continues to reach new heights, but future growth will be harder to sustain. At the same time, the cycle is becoming increasingly fragmented, with casualty, property and reinsurance markets beginning to follow different trajectories. As broad pricing tailwinds become less reliable, future performance is likely to depend less on market momentum and more on strategic choices, disciplined execution and effective performance management.
From Hard Market Returns to Sustainable Advantage
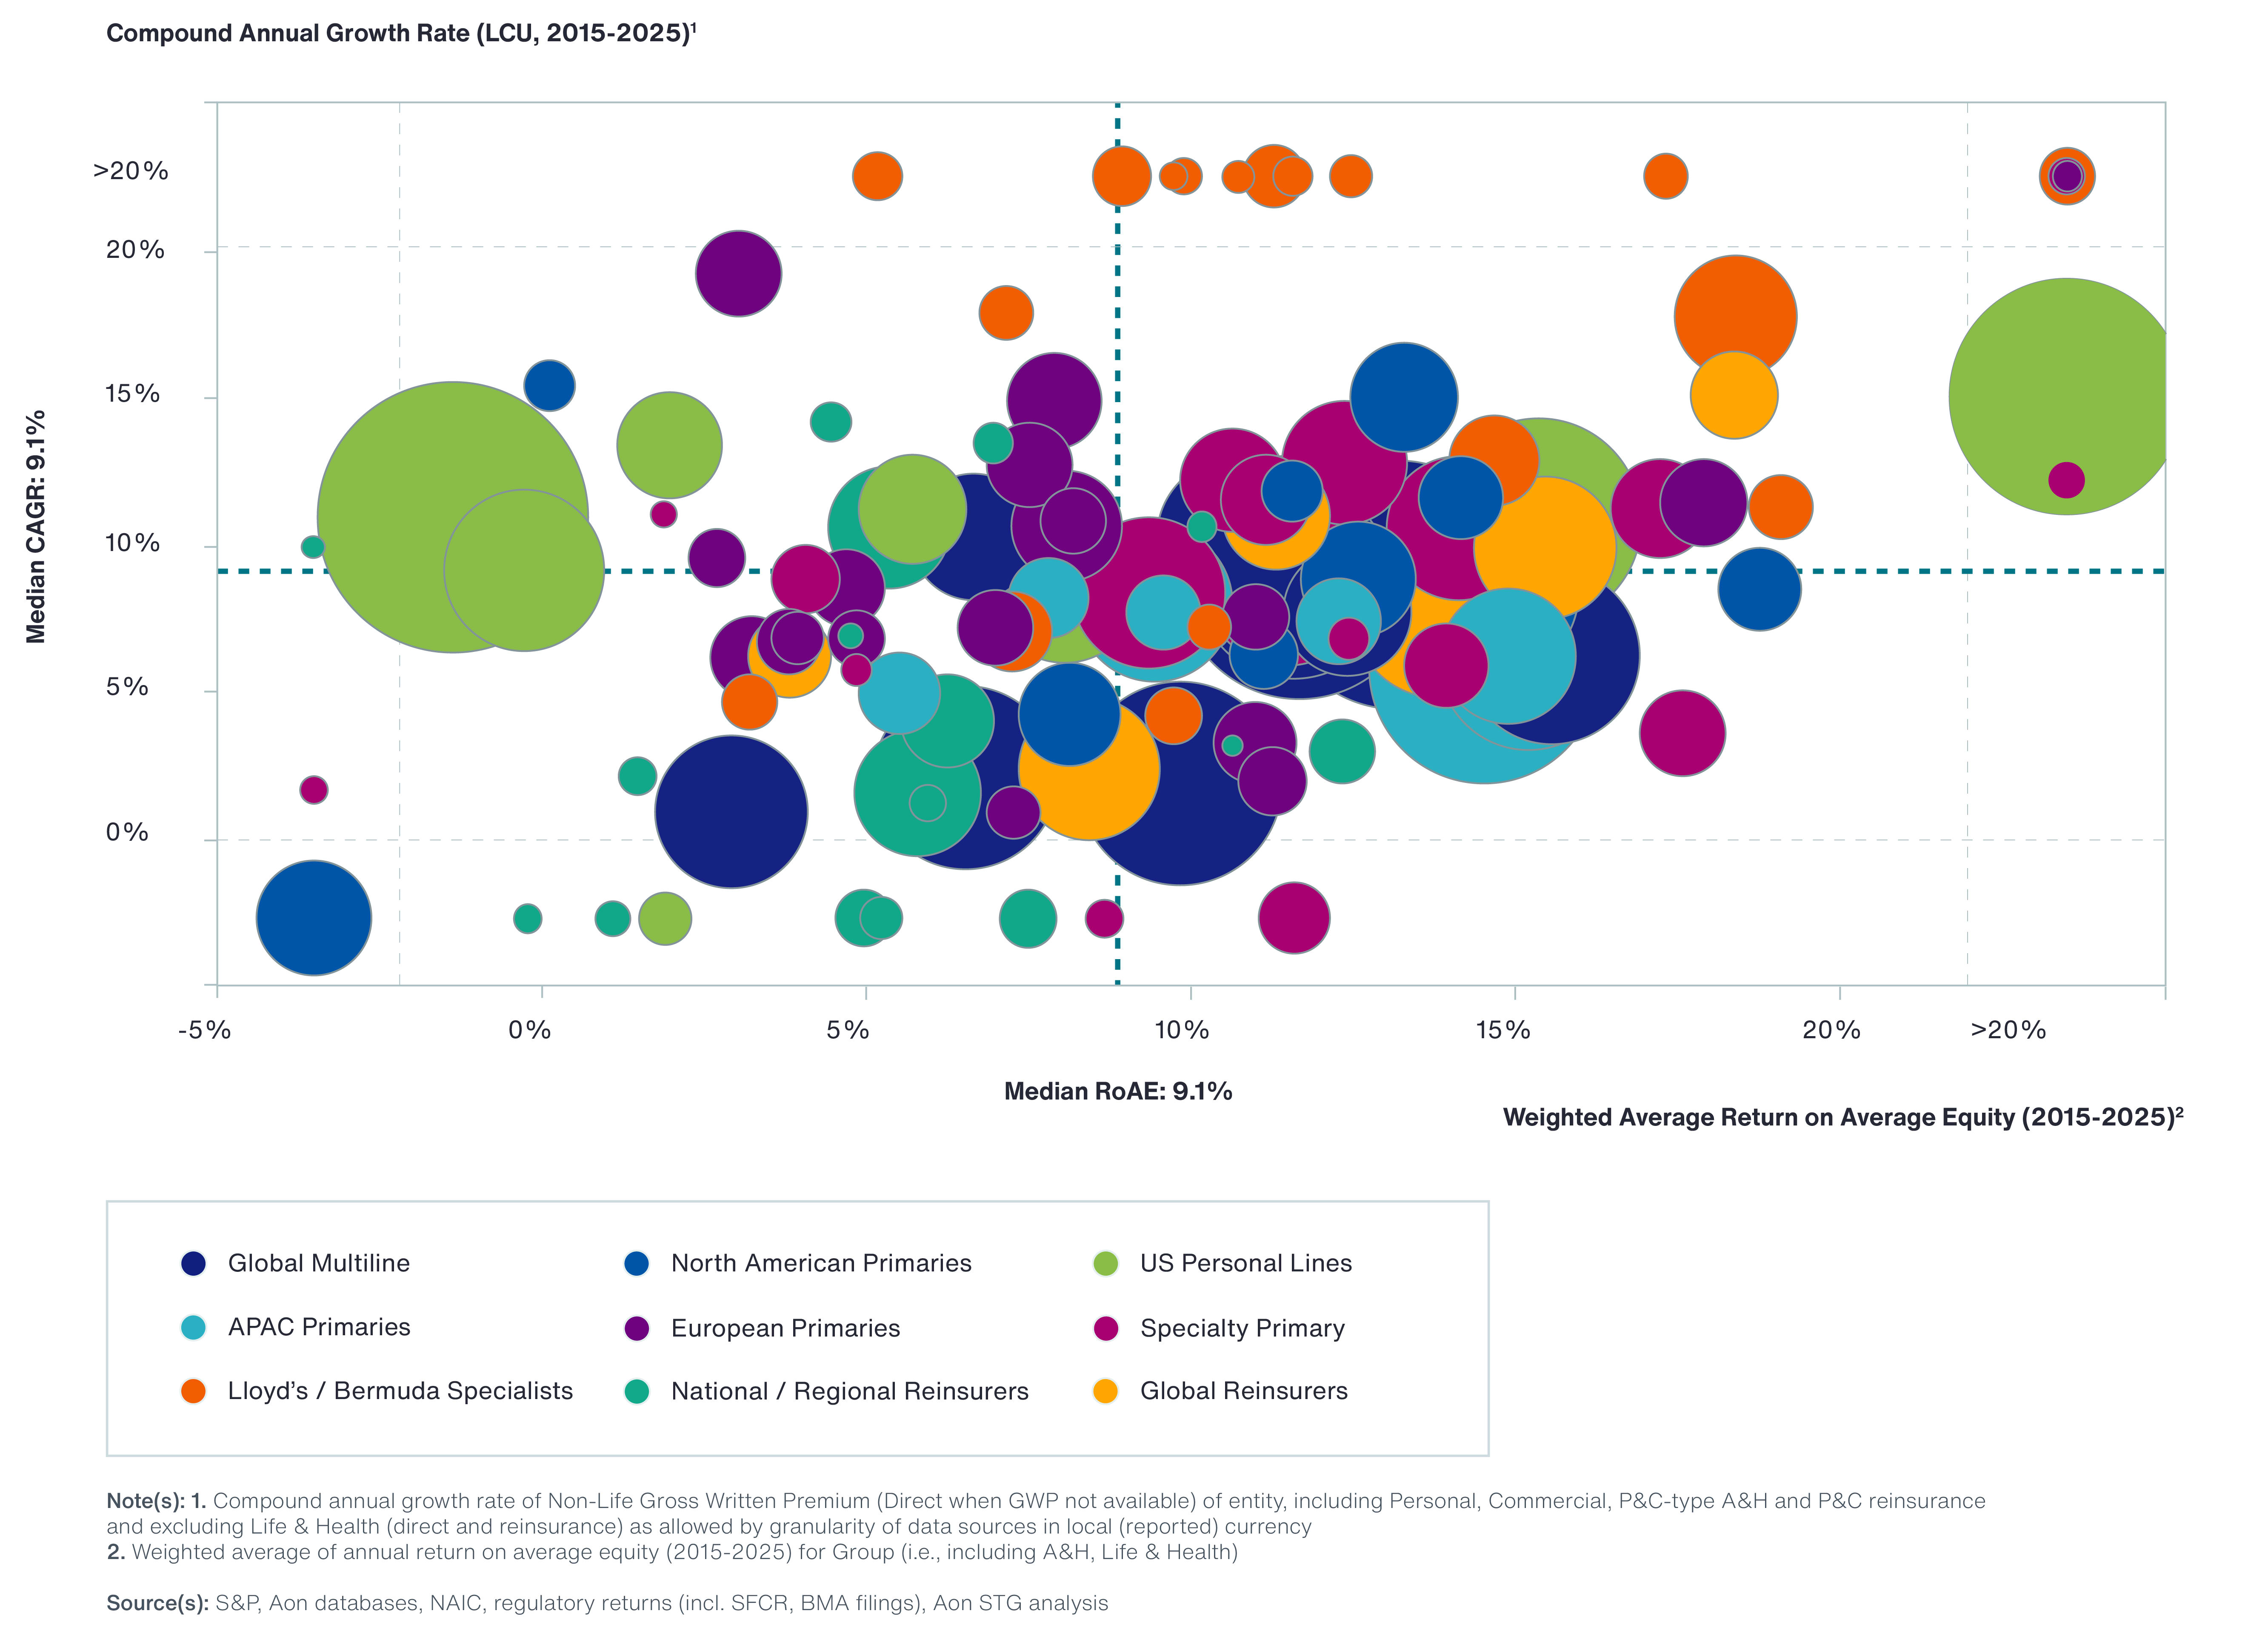
Our updated market-positioning analysis shows not just who improved, but how the market has shifted:
- Profitability remains exceptionally strong. Return on average equity (RoAE) reached 16.8% in 2025, the highest level observed since Aon began tracking the cohort in 2009 and the fifth consecutive year of improvement since the downturn in 2020. Continued growth in underwriting income was the principal driver of stronger returns, supported by a benign catastrophe year, improvements in underwriting performance and favourable market conditions that may not last.
- Fewer carriers are achieving sustainable growth in returns. the proportion of carriers increasing RoAE year-on-year declined from 74% to 60%, suggesting that gains are becoming less broad-based as the cycle evolves.
- Underwriting performance is at a decade high. The combined operating ratio (COR) improved to 91.1%, the lowest level of the decade.
- Growth is becoming harder to sustain. Premium growth declined for a fourth straight year to 5.2%, below the decade average and less than half the level seen in 2021. The gap between growth and profitability continues to widen, creating a markedly different operating environment from earlier in the cycle.
- Performance is diverging. The spread of combined ratios and RoAE widened across the different segments in property and casualty, with globally diversified and specialist carriers continuing to perform strongly.
Stronger industry profitability does not mean all insurers are equally well positioned for the next phase of the cycle. Some have converted favourable pricing conditions into structurally stronger returns. Others remain constrained by catastrophe exposure, capital intensity, operating complexity or lack of differentiation.
The question is no longer whether insurers can capture the benefits of favourable market conditions. It is: how can they sustain profitable growth as the hard-market tailwinds fade and the opportunity to rely on pricing momentum diminishes?
The hard market rewarded many different strategies. The next phase of the cycle will be less forgiving. The insurers that outperform are likely to be those that combine disciplined growth choices with relentless execution.
5 Pitfalls for Insurers to Avoid in the Next Phase of the Cycle
-
1. Don't Confuse Strong Returns with Sustainable Growth
The findings point to a clear tension: profitability has improved significantly with RoAE and COR reaching decade-leading levels, yet premium growth continues to slow. Strong earnings should therefore be viewed as an opportunity to build future advantage, not as a guarantee of sustainable growth. Not all of the recent improvement in returns is likely to be structural. Strong underwriting income has benefited from favourable market conditions, including benign catastrophe activity and cyclical tailwinds that may not persist indefinitely. Leaders therefore need to distinguish between earnings improvements that reflect enduring capability advantages and those that are more dependent on market conditions.
Leaders should ask:
- Are current returns sustainable?
- Which earnings drivers are structural?
- Which are cyclical?
In practice: Focus on identifying which sources of earnings are structural and building growth plans that do not depend on continued rate increases.
-
2. Don’t Chase Premium Growth at Any Cost
As growth slows, profitable growth will increasingly depend on where insurers choose to compete and how effectively they deploy capital, underwriting expertise and distribution capabilities. Future leaders are likely to be more selective, prioritising opportunities that combine profitability, resilience and differentiated client relevance.
Leaders should ask:
- Where do we have a genuine competitive advantage?
- Which opportunities create both profitability and resilience?
- Are we pursuing growth for value creation or for scale?
In practice: Prioritise growth opportunities where the organisation has a clear opportunity to win and where resilience, relevance and profitability reinforce one another.
-
3. Don’t Treat Capital as Just a Safety Net
Stronger profitability has created greater strategic flexibility. Leading insurers will increasingly use capital as an active performance management tool, balancing growth ambitions with flexibility, resilience and return optimisation. The question is how effectively that flexibility is deployed to support future growth.
Leaders should ask:
- Are we deploying capital to its highest-value opportunities?
- Does our capital structure support our growth ambitions?
- Could reinsurance or alternative capital unlock additional flexibility?
In practice: Use capital as a strategic lever to improve growth, resilience and returns, rather than simply a constraint to manage.
-
4. Don’t Underinvest in People and Technology
As pricing momentum becomes a less reliable driver of performance, competitive advantage will depend increasingly on an organisation's ability to execute, adapt and continually improve decision quality. Future leaders will invest not only in technology, but also in the underwriting, operating and talent capabilities required to translate strategy into measurable performance.
Leaders should ask:
- Do we have the digital and organisational capabilities needed to execute our strategy successfully?
- Which investments and strategic transactions will have the greatest impact on future performance?
- Are we building competitive advantage faster than market conditions are changing?
In practice: Prioritise the talent, technology and operating capabilities that improve execution, decision quality and long-term earnings power.
-
5. Don’t Let AI Become Someone Else’s Advantage
As market conditions diverge and performance gaps widen, insurers need new sources of competitive advantage. AI has the potential to improve underwriting decisions, enhance risk selection and increase productivity across the value chain. The risk is not simply failing to adopt AI, but allowing competitors to make faster, more informed decisions and build advantages that become increasingly difficult to close.
Leaders should ask:
- Where could AI improve underwriting decisions, productivity or portfolio performance most significantly?
- Are we using AI to enhance decision-making and reimagining how we work, or simply automating existing processes?
- If a competitor successfully scaled AI across the business tomorrow, where would we be most vulnerable?
In practice: Focus AI investments on improving underwriting quality, decision-making and operational effectiveness rather than technology adoption alone.
The hard market restored profitability. It did not eliminate the need for differentiation.
From Strong Returns to Sustainable Advantage
Insurers now enter the next phase of the cycle from a position of considerable strength. Yet sustaining today’s levels of profitability will become increasingly challenging as growth slows, pricing momentum moderates and market conditions diverge across segments.
The winners will not be defined by who benefited most from favourable conditions, but by who used those conditions most effectively to build sustainable advantage.
General Disclaimer
This document is not intended to address any specific situation or to provide legal, regulatory, financial, or other advice. While care has been taken in the production of this document, Aon does not warrant, represent or guarantee the accuracy, adequacy, completeness or fitness for any purpose of the document or any part of it and can accept no liability for any loss incurred in any way by any person who may rely on it. Any recipient shall be responsible for the use to which it puts this document. This document has been compiled using information available to us up to its date of publication and is subject to any qualifications made in the document.
Terms of Use
The contents herein may not be reproduced, reused, reprinted or redistributed without the expressed written consent of Aon, unless otherwise authorized by Aon. To use information contained herein, please write to our team.
Aon's Better Being Podcast
Our Better Being podcast series, hosted by Aon Chief Wellbeing Officer Rachel Fellowes, explores wellbeing strategies and resilience. This season we cover human sustainability, kindness in the workplace, how to measure wellbeing, managing grief and more.
-
Podcast 23 mins
Better Being Series: Understanding Burnout in the Workplace -
Podcast 14 mins
Better Being Series: Why Nutrition Matters -
Podcast 10 mins
Better Being Series: Discover the ‘Blue Zones’ Where People Live Longer -
Podcast 20 mins
Better Being Series: Improving Your Financial Wellbeing -
Podcast 17 mins
Better Being Series: Are You Taking Care of Your Digital Wellbeing? -
Podcast 19 mins
On Aon Podcast: Better Being Series Dives into Women’s Health -
Podcast 25 mins
On Aon’s Better Being Series: Managing Loss and Grief

Aon Insights Series Asia
Expert Views on Today's Risk Capital and Human Capital Issues
-
Article 8 mins
Thriving in an Interconnected World: How the C-Suite Embraces Uncertainty -
Article 6 mins
Powering Progress: Collaborating to Build a Sustainable Future in Emerging Markets -
Article 5 mins
Building Business Resilience: Key Steps to Effectively Integrate Risk Management Across Your Organisation -
Article 7 mins
Why Humans Are the Essential Factor in the Success of Artificial Intelligence (AI) -
Article 5 mins
Leveraging Research and Expertise to Strengthen Your HR Strategy for 2025 and Beyond -
Article 5 mins
Managing Risk on the Energy Transition Journey -
Article 7 mins
The Role of Risk Management in the Age of Generative Artificial Intelligence -
Article 7 mins
Finding A Way In Asia Pacific's New Economic Reality -
Article 4 mins
Three Ways to Boost Value from Benefits: APAC Insights from LinkedIn


Aon Insights Series Pacific
Expert Views on Today's Risk Capital and Human Capital Issues
-
Article 3 mins
Article Template to Duplicate

Aon Insights Series UK
Expert Views on Today's Risk Capital and Human Capital Issues
-
Article 2 mins
Introduction: Clarity and Confidence to Act Now -
Article 11 mins
Navigating a New Age of Macroeconomic Uncertainty -
Article 3 mins
Making Better Decisions — A C-Suite Perspective -
Article 3 mins
Understanding the Dynamics of Today’s Workforce — Reward, Retain, Evolve -
Article 3 mins
Artificial Intelligence — Managing the Risk and Potential -
Article 10 mins
Unlocking Balance Sheet Value to Empower Your Business Strategy -
Article 3 mins
Navigating the Unpredictable: Aon’s Suite of Actionable Analytics -
Article 4 mins
Redefining Risk Capital as a Business Enabler: Veolia's Innovative Approach -
Article 9 mins
A Data-Driven Approach to Better Workforce Decisions -
Article 5 mins
The Importance of Pay Transparency -
Article 6 mins
How Human Capital Data Enhances Risk Management for Financial Institutions -
Article 4 mins
The Battle for Top Talent in the Professional Services Sector -
Article 5 mins
Insights on a Volatile World — Risk Factors That Businesses Need to be Monitoring


Client Trends 2025
Better Decisions Across Interconnected Risk and People Issues.
-

Article 3 mins
Acknowledging Our Complex Reality -
Article 10 mins
Trade in a Technology-Driven Future -
Article 9 mins
How AI and Workforce will Intersect: Navigating Risks and Opportunities -
Article 8 mins
Weather and Workforce: Employers Must Quantify the Risk -
Article 9 mins
Steering Trade and Supply Chains Amid Weather Challenges -
Report 13 mins
Trade Issues Confront Global Businesses on Multiple Fronts -
Report 19 mins
Technology is Driving Firms to Harness Opportunities and Defend Against Threats -
Report 19 mins
Climate Analytics Unlock Capital to Protect People and Property -
Report 14 mins
A Workforce in Transition Prepares to Meet a Host of Challenges


Construction and Infrastructure
The construction industry is under pressure from interconnected risks and notable macroeconomic developments. Learn how your organization can benefit from construction insurance and risk management.
-
Article 8 mins
How North American Construction Contractors Can Mitigate Emerging Risks -
Article 7 mins
Managing Construction Risks: 7 Risk Advisory Steps -
Article 7 mins
Unlocking Capacity and Capital in a Challenging Construction Risk Market -
Article 7 mins
Protecting North American Contractors from Extreme Heat Risks with Parametric -
Article 5 mins
How Climate Modeling Can Mitigate Risks and Improve Resilience in the Construction Industry -
Report 1 mins
Construction Risk Management Europe Report 2023 -
Article 8 mins
Parametric Can Help Mitigate Extreme Heat Risks for Contractors in EMEA


Cyber Resilience
Our Cyber Resilience collection gives you access to Aon’s latest insights on the evolving landscape of cyber threats and risk mitigation measures. Reach out to our experts to discuss how to make the right decisions to strengthen your organization’s cyber resilience.
-

Article 8 mins
Cyber and E&O Market Conditions Remain Favorable Amid Emerging Global Risks -
Article 7 mins
How to Navigate AI-Driven Cyber Risks -
Article 9 mins
Building Resilience in a Buyer-Friendly Cyber and E&O Market -
Article 11 mins
A Middle Market Roadmap for Cyber Resilience -
Article 7 mins
Lessons Learned from the CrowdStrike Outage: 5 Strategies to Build Cyber Resilience -
Article 8 mins
Responding to Cyber Attacks: How Directors and Officers and Cyber Policies Differ -
Article 6 mins
Why Now is the Right Time to Customize Cyber and E&O Contracts


Employee Wellbeing
Our Employee Wellbeing collection gives you access to the latest insights from Aon's human capital team. You can also reach out to the team at any time for assistance with your employee wellbeing needs.
-
Article 8 mins
Employer Strategies for Cancer Prevention and Treatment -
Article 6 mins
The Long-Term Care Conundrum in the United States -
Article 9 mins
Developing a Paid Leave Strategy That Supports Workers and Their Families -
Article 9 mins
4 Ways to Foster a Thriving Workforce Amid Rising Health Costs -
Article 9 mins
The Next Evolution of Wellbeing is About Performance -
Article 6 mins
Three Ways Collective Retirement Plans Support HR Priorities -
Article 9 mins
How the Right Employee Wellbeing Strategy Impacts Microstress and Burnout at Work -
Podcast 13 mins
On Aon Podcast: The Future of Healthcare: Key Factors Impacting Medical Trend Rates -
Article 7 mins
Making Wellbeing Part of a Company’s DNA -
Article 7 mins
A Comprehensive Approach to Financial Wellbeing


Environmental, Social and Governance Insights
Explore Aon's latest environmental social and governance (ESG) insights.
Q4 2023 Global Insurance Market Insights
Our Global Insurance Market Insights highlight insurance market trends across pricing, capacity, underwriting, limits, deductibles and coverages.
-
Article 12 mins
Q4 2023: Global Insurance Market Overview -
Article 13 mins
Top Risk Trends to Watch in 2024


Global Risk Management Survey
Better Decisions Across Interconnected Risk and People Issues.
-
Report 28 mins
A New Era of Converging Risks and Accelerating Disruption -
Article 1 mins
Top 10 Global Risks -
Article 1 mins
Industry Insights: Findings from Aon's Global Risk Management Survey -
Article 1 mins
Regional Results -
Article 41 mins
Country-Level Findings -
Report 5 mins
Methodology and Respondent Demographics


Regional Results
How do the top risks on business leaders’ minds differ by region and how can these risks be mitigated? Explore the regional results to learn more.
-
Article 12 mins
Rethinking Resilience: Addressing Asia Pacific’s Top Risks -
Article 10 mins
Turning Uncertainty into Opportunity: Managing Risk in the EMEA Region -
Article 10 mins
Latin America’s Risk Landscape: Turning Complexity into Competitive Advantage -

Article 10 mins
Rethinking Resilience: Navigating North America’s Evolving Risk Landscape


Impact Report 2025
Explore Aon's corporate sustainability impact and strategy.
-
Article 7 mins
Executive Summary -
Article 13 mins
Aon’s Environmental Sustainability -
Article 15 mins
Supporting Energy Resilience and a Transition to a Low-Carbon Economy -
Article 20 mins
Our Commitment to Our Colleagues -
Article 8 mins
Our Community Impact -
Article 10 mins
Governance -
Article 8 mins
Cyber and Data Security -
Article 11 mins
Redefining Resilience


Top 10 Global Risks
Trade, technology, weather and workforce stability are the central forces in today’s risk landscape.
-
Article 6 mins
Cyber Risk: Turning Uncertainty into Opportunity -
Article 7 mins
Business Interruption: Managing Risk in an Interconnected World -
Article 6 mins
Why Economic Slowdown is an Ongoing Risk for Organizations -
Article 8 mins
Navigating Regulatory and Legislative Change -
Article 5 mins
Increasing Competition Is Intensifying Risk for Organizations -
Article 7 mins
Commodity Price Risk and Material Scarcity: An Escalating and Complex Risk -
Article 9 mins
Supply Chain or Distribution Failure: Navigating the New Normal -
Article 5 mins
Damage to Reputation or Brand: A Critical Risk -
Article 6 mins
Geopolitical Volatility: Preparing for the Unpredictable -
Article 6 mins
Cash Flow and Liquidity Risk: A Rising Challenge


Industry Insights
These industry-specific articles explore the top risks, their underlying drivers and the actions leaders are taking to build resilience.
-
Article 9 mins
Building Resilience to Support Growth in Construction and Real Estate -

Article 10 mins
Managing Risk and Unlocking Opportunity in the Food, Agribusiness and Beverage Industry -

Article 8 mins
Adapting to Disruption: How Financial Institutions are Reframing Risk -
Article 10 mins
Turning Risk into Resilience in the Industrials and Manufacturing Industry -
Article 11 mins
Navigating Risk in Insurance: Turning Complexity into Competitive Advantage -

Article 10 mins
Navigating Risk in Life Sciences: Building Resilience to Support Growth -
Article 11 mins
Navigating Volatility in Natural Resources: Risk Management as a Value Driver -

Article 10 mins
Navigating Risk in Transportation and Logistics: Gearing Up for Big Transitions -
Article 9 mins
Technology, Media and Communications: Rethinking Risk in a Shifting Landscape


Human Capital Analytics
Our Human Capital Analytics collection gives you access to the latest insights from Aon's human capital team. Contact us to learn how Aon’s analytics capabilities helps organizations make better workforce decisions.
-

Article 35 mins
5 Human Resources Trends to Watch in 2025 -
Article 13 mins
Medical Rate Trends and Mitigation Strategies Across the Globe -
Article 9 mins
3 Strategies to Help Avoid Workers Compensation Claims Litigation -
Podcast 15 mins
On Aon Podcast: Using Data and Analytics to Improve Health Outcomes -
Article 14 mins
How Technology Will Transform Employee Benefits in the Next Five Years -
Podcast 18 mins
On Aon Podcast: Technology Impacting the Future of Health and Benefits -
Article 10 mins
Designing Tomorrow: Personalizing EVP, Benefits and Total Rewards


Human Capital Quarterly Insights Briefs
Read our collection of human capital articles that explore in depth hot topics for HR and risk professionals, including using data and analytics to measure total rewards programs, how HR and finance can better partner and the impact AI will have on the workforce.
-
Article 12 mins
Total Rewards Strategies That Drive Business Outcomes -
Article 35 mins
5 Human Resources Trends to Watch in 2025 -
Article 20 mins
5 Ways HR Can Partner with Finance to Drive Growth -
Article 15 mins
How Artificial Intelligence is Transforming Human Resources and the Workforce -
Article 15 mins
Five Big Human Resources Trends to Watch in 2024 -
Article 10 mins
Designing Tomorrow: Personalizing EVP, Benefits and Total Rewards -
Article 10 mins
How Data and Analytics Can Optimize HR Programs -
Article 15 mins
Get Ready for the Top 5 HR Trends in 2023


Insights for HR
Explore our hand-picked insights for human resources professionals.
-
Article 7 mins
COVID-19 has Permanently Changed the Way We Think About Wellbeing -
Article 10 mins
How Data and Analytics Can Optimize HR Programs -
Article 7 mins
Case Study: The LPGA Unlocks Talent Potential with Data -
Article 10 mins
Navigating the New EU Directive on Pay Transparency -
Article 6 mins
Rethinking Your Total Rewards Programs During Mergers and Acquisitions


Workforce
Our Workforce Collection provides access to the latest insights from Aon’s Human Capital team on topics ranging from health and benefits, retirement and talent practices. You can reach out to our team at any time to learn how we can help address emerging workforce challenges.
-
Article 8 mins
Weather and Workforce: Employers Must Quantify the Risk -
Article 12 mins
Total Rewards Strategies That Drive Business Outcomes -
Article 8 mins
AI and Workforce Skills: Who Should Act and Why Now? -
Article 19 mins
3 Strategies to Promote an Inclusive Environment and Bridge the Gender Gap -
Article 8 mins
2025 Salary Increase Planning Tips -
Article 12 mins
People Risks Are Rising: Here’s How U.S. Benefits Are Stepping Up -
Article 8 mins
Employer Strategies for Cancer Prevention and Treatment -
Article 6 mins
Taking a Data-Led Approach to Job Architecture to Accelerate Pay Transparency -
Podcast 12 mins
Better Being Series: Building Sustainable Performance in a Multi-Generational Workforce -
Article 7 mins
Key Trends in U.S. Benefits for 2025 and Beyond -
Article 7 mins
Why Pay Transparency Demands a Total Rewards Lens -
Article 9 mins
4 Ways to Foster a Thriving Workforce Amid Rising Health Costs


Mergers and Acquisitions
Our Mergers and Acquisitions (M&A) collection gives you access to the latest insights from Aon's thought leaders to help dealmakers make better decisions. Explore our latest insights and reach out to the team at any time for assistance with transaction challenges and opportunities.
-
Article 6 mins
Rethinking Your Total Rewards Programs During Mergers and Acquisitions -
Article 9 mins
Organizational Design and Talent Planning are Key to M&A Success -
Article 5 mins
Project Management for HR: The Secret Behind a Successful M&A Deal -
Article 8 mins
Cultural Alignment Planning Drives M&A Success -
Report 1 mins
A Guide to Maximizing Value in Post-Merger Integrations -
Report 2 mins
The ABC's of Private Equity M&A: Deal Flow Impacts of Al, Big Tech and Climate Change -
Article 11 mins
The Silver Lining on M&A Deal Clouds: M&A Insurance Insights from 2023


Natural Resources and Energy Transition
The challenges in adopting renewable energy are changing with technological advancements, increasing market competition and numerous financial support mechanisms. Learn how your organization can benefit from our renewables solutions.
-
Article 4 mins
5 Steps for Successful Carbon Accounting Verification -
Article 6 mins
AI Innovations in Renewable Energy: Transforming the Sector -
Article 11 mins
Securing Human Capital in Natural Resources -
Article 6 mins
Decarbonizing Construction for a Low-Emission Future


Navigating Volatility
How do businesses navigate their way through new forms of volatility and make decisions that protect and grow their organizations?
Parametric Insurance
Our Parametric Insurance Collection provides ways your organization can benefit from this simple, straightforward and fast-paying risk transfer solution. Reach out to learn how we can help you make better decisions to manage your catastrophe exposures and near-term volatility.
-
Article 10 mins
How Public Entities and Businesses Can Use Parametric for Emergency Funding -
Article 6 mins
Parametric Insurance: A Complement to Traditional Property Coverage -
Article 8 mins
Using Parametric Insurance to Match Capital to Climate Risk -
Article 6 mins
Using Parametric Insurance to Close the Earthquake Protection Gap -
Article 5 mins
How Technology Enhancements are Boosting Parametric


Pay Transparency and Equity
Our Pay Transparency and Equity collection gives you access to the latest insights from Aon's human capital team on topics ranging from pay equity to diversity, equity and inclusion. Contact us to learn how we can help your organization address these issues.
-
Article 6 mins
Taking a Data-Led Approach to Job Architecture to Accelerate Pay Transparency -
Article 19 mins
3 Strategies to Promote an Inclusive Environment and Bridge the Gender Gap -
Report 1 mins
The 2024 North America Pay Transparency Readiness Study -
Article 10 mins
How Financial Institutions can Prepare for Pay Transparency Legislation -
Article 8 mins
Pay Transparency Can Lead to Better Equity Across Benefits -
Article 12 mins
Understanding and Preparing for the Rise in Pay Transparency -
Podcast 14 mins
On Aon Podcast: Understanding Pay Transparency Regulations -
Article 10 mins
Navigating the New EU Directive on Pay Transparency -
Article 6 mins
To Disclose Pay or Not? How Companies are Approaching the Pay Transparency Movement -
Podcast 19 mins
On Aon Podcast: Better Being Series Dives into Women’s Health -
Article 11 mins
Advancing Women’s Health and Equity Through Benefits and Support


Property Risk Management
Forecasters are predicting an extremely active 2024 Atlantic hurricane season. Take measures to build resilience to mitigate risk for hurricane-prone properties.
-
Article 8 mins
Florida Hurricanes Not Expected to Adversely Affect Property Market -
Article 10 mins
Build Resilience for an Extremely Active Atlantic Hurricane Season -
Article 4 mins
Four Steps to Develop Strong Property Risk Coverage in a Hardening Market -
Podcast 16 mins
On Aon Podcast: Navigating and Preparing for Catastrophes -
Article 6 mins
Parametric Insurance: A Complement to Traditional Property Coverage -
Article 4 mins
Navigating Climate Risk Using Multiple Models and Data Sets -
Article 5 mins
Rising Losses From Severe Convection Storms Mostly Explained by Exposure Growth -
Article 6 mins
Using Parametric Insurance to Close the Earthquake Protection Gap


Technology
Our Technology Collection provides access to the latest insights from Aon's thought leaders on navigating the evolving risks and opportunities of technology. Reach out to the team to learn how we can help you use technology to make better decisions for the future.
-
Article 9 mins
How AI and Workforce will Intersect: Navigating Risks and Opportunities -
Article 23 mins
The AI Data Center Boom: Strategies for Sustainable Growth and Risk Management -
Article 8 mins
AI and Workforce Skills: Who Should Act and Why Now? -
Article 7 mins
How Technology is Transforming Open Enrollment in the U.S. -
Article 15 mins
Navigating Cyber Risks in EMEA: Key Insights for 2025 -
Article 7 mins
How to Navigate AI-Driven Cyber Risks -
Article 15 mins
How Artificial Intelligence is Transforming Human Resources and the Workforce -
Podcast 9 mins
On Aon Podcast: How has CrowdStrike Changed the Cyber Market? -
Article 18 mins
5 Ways Artificial Intelligence can Boost Claims Management -
Article 12 mins
Navigating AI-Related Risks: A Guide for Directors and Officers -
Article 5 mins
How Technology Enhancements are Boosting Parametric -
Article 7 mins
How to Futureproof Data and Analytics Capabilities for Reinsurers


Trade
Our Trade Collection gives you access to the latest insights from Aon's thought leaders on navigating the evolving risks and opportunities for international business. Reach out to our team to understand how to make better decisions around macro trends and why they matter to businesses.
-
Article 10 mins
Trade in a Technology-Driven Future -
Podcast 9 mins
Special Edition: Global Trade and its Impact on Supply Chain -
Article 8 mins
The Evolving Threat of Cargo Theft: 5 Key Mitigation Strategies -
Report 1 mins
Findings from Aon's Global Risk Management Survey | Tenth Edition -
Article 4 mins
Four Steps to Develop Strong Property Risk Coverage in a Hardening Market -
Article 14 mins
Cutting Supply Chains: How to Achieve More Reward with Less Risk -
Article 9 mins
Driving Private Equity Value Creation Through Credit Solutions -
Article 7 mins
4 Steps to Help Take Advantage of a Buyer-Friendly Directors' & Officers' Market -
Article 8 mins
Managing Reputational Risks in Global Supply Chains -
Article 8 mins
How an Outsourced Chief Investment Officer Can Help Improve Governance and Manage Complexity -
Article 8 mins
Decarbonizing Your Business: Finding the Right Insurance and Strategy -
Article 8 mins
Reputation Analytics as a Leading Indicator of ESG Risk


Transaction Solutions Global Claims Study
Better Decisions Across Interconnected Risk and People Issues.
-

Report 5 mins
Chapter 1: Author’s Note & Executive Summary -

Report 8 mins
Chapter 2: North America: Highlights, Claims Severity and Frequency -
Report 3 mins
Chapter 3: North America: Breach Type and Notification -

Report 24 mins
Chapter 4: North America: Industry Sectors and Trends -
Report 5 mins
Chapter 5: North America: Tax Insurance Claims -
Report 5 mins
Chapter 6: EMEA: Highlights and Introduction -
Report 9 mins
Chapter 7: EMEA: Claim Frequency and Metrics -
Report 7 mins
Chapter 8: EMEA: Notifications by Target Location and Claims Severity and Payment Trends -

Report 10 mins
Chapter 9: EMEA: Breach Types and Trends -
Report 7 mins
Chapter 10: EMEA: Case Law, Insurer Survey, Claims Handling and Tax -

Report 6 mins
Chapter 11: APAC: Asia -

Report 9 mins
Chapter 12: APAC: Pacific


Weather
With a changing climate, organizations in all sectors will need to protect their people and physical assets, reduce their carbon footprint, and invest in new solutions to thrive. Our Weather Collection provides you with critical insights to be prepared.
-
Article 9 mins
Steering Trade and Supply Chains Amid Weather Challenges -
Podcast 9 mins
On Aon Podcast: Climate Impact on the Property and Casualty Market -
Alert 14 mins
L.A. Wildfires Highlight Urgent Need for Employee Support and Business Resilience -
Report 3 mins
2026 Climate and Catastrophe Insight -
Article 10 mins
How Public Entities and Businesses Can Use Parametric for Emergency Funding -
Podcast 12 mins
On Aon Podcast: Tackling Climate Risk to Build Economic Resilience -
Article 5 mins
Understanding Freeze Risk in a Changing Climate -
Podcast 9 mins
On Aon Podcast: Climate Science Through Academic Collaboration -
Article 6 mins
How Companies Are Using Climate Modeling to Improve Risk Decisions -
Article 8 mins
Using Parametric Insurance to Match Capital to Climate Risk -
Article 9 mins
Record Heatwaves: Protecting Employee Health and Safety


Workforce Resilience
Our Workforce Resilience collection gives you access to the latest insights from Aon's Human Capital team. You can reach out to the team at any time for questions about how we can assess gaps and help build a more resilience workforce.

More Like This
-

Article 8 mins
As Climate Volatility Intensifies, FAB Leaders are Rethinking Risk
Climate volatility is reshaping the food, agribusiness and beverage value chain, driving disruption across production, supply chains and pricing. Organizations that can quantify exposure and apply data driven risk strategies are better positioned to protect margins and sustain performance.
-
Article 7 mins
Commuter Rail Liability Cap Increase: How Rail Agencies Should Respond
The U.S. passenger rail liability cap recently rose to $401.9 million, adjusted for inflation after five years. While the increase was expected, it brings immediate challenges for commuter railroads facing tight budgets and a hardened excess liability market.
-
Article 8 mins
Insurability Starts at Design for Wet Risk Construction
Wet risk construction projects present some of the market’s most complex exposures, with losses often driven by temporary works, groundwater, flooding and sequencing. Tackling insurability at the design phase can improve resilience, broaden cover and deliver more predictable outcomes.


